Skip to Main Content

Asset Allocation Update: Tech equities defy rising yields and AI warnings

Despite higher yields, we remain constructive. We consider the additional rate hikes priced in to be exaggerated and do not expect a new tightening cycle. Thanks to solid fundamentals, we continue to prefer equities, focusing on tech and cyclicals. Silver and AUD government bonds serve as a hedge.

Author: Roger Rüegg

US tech equities are recording earnings growth of over 70 per cent this year (Image: iStock.com).

What adjustments have we made to the portfolios?

Our bond experts favour subordinated bonds from companies with good ratings. These offer a clearly higher credit spread in some cases at moderately higher risk. We share this view and are adding corporate hybrids.

Over the medium term, we still expect a weaker USD, but in the short term the positive momentum could persist due to the restored independence of the Fed and the strength of the US economy.

The outperformance of small caps was short-lived and earnings developments now favour large caps again. High interest rates are a burden. We are therefore switching from global small caps into North American equities, thereby again increasing our tech allocation in the portfolio.

Bonds: yields now rising for CHF bonds as well

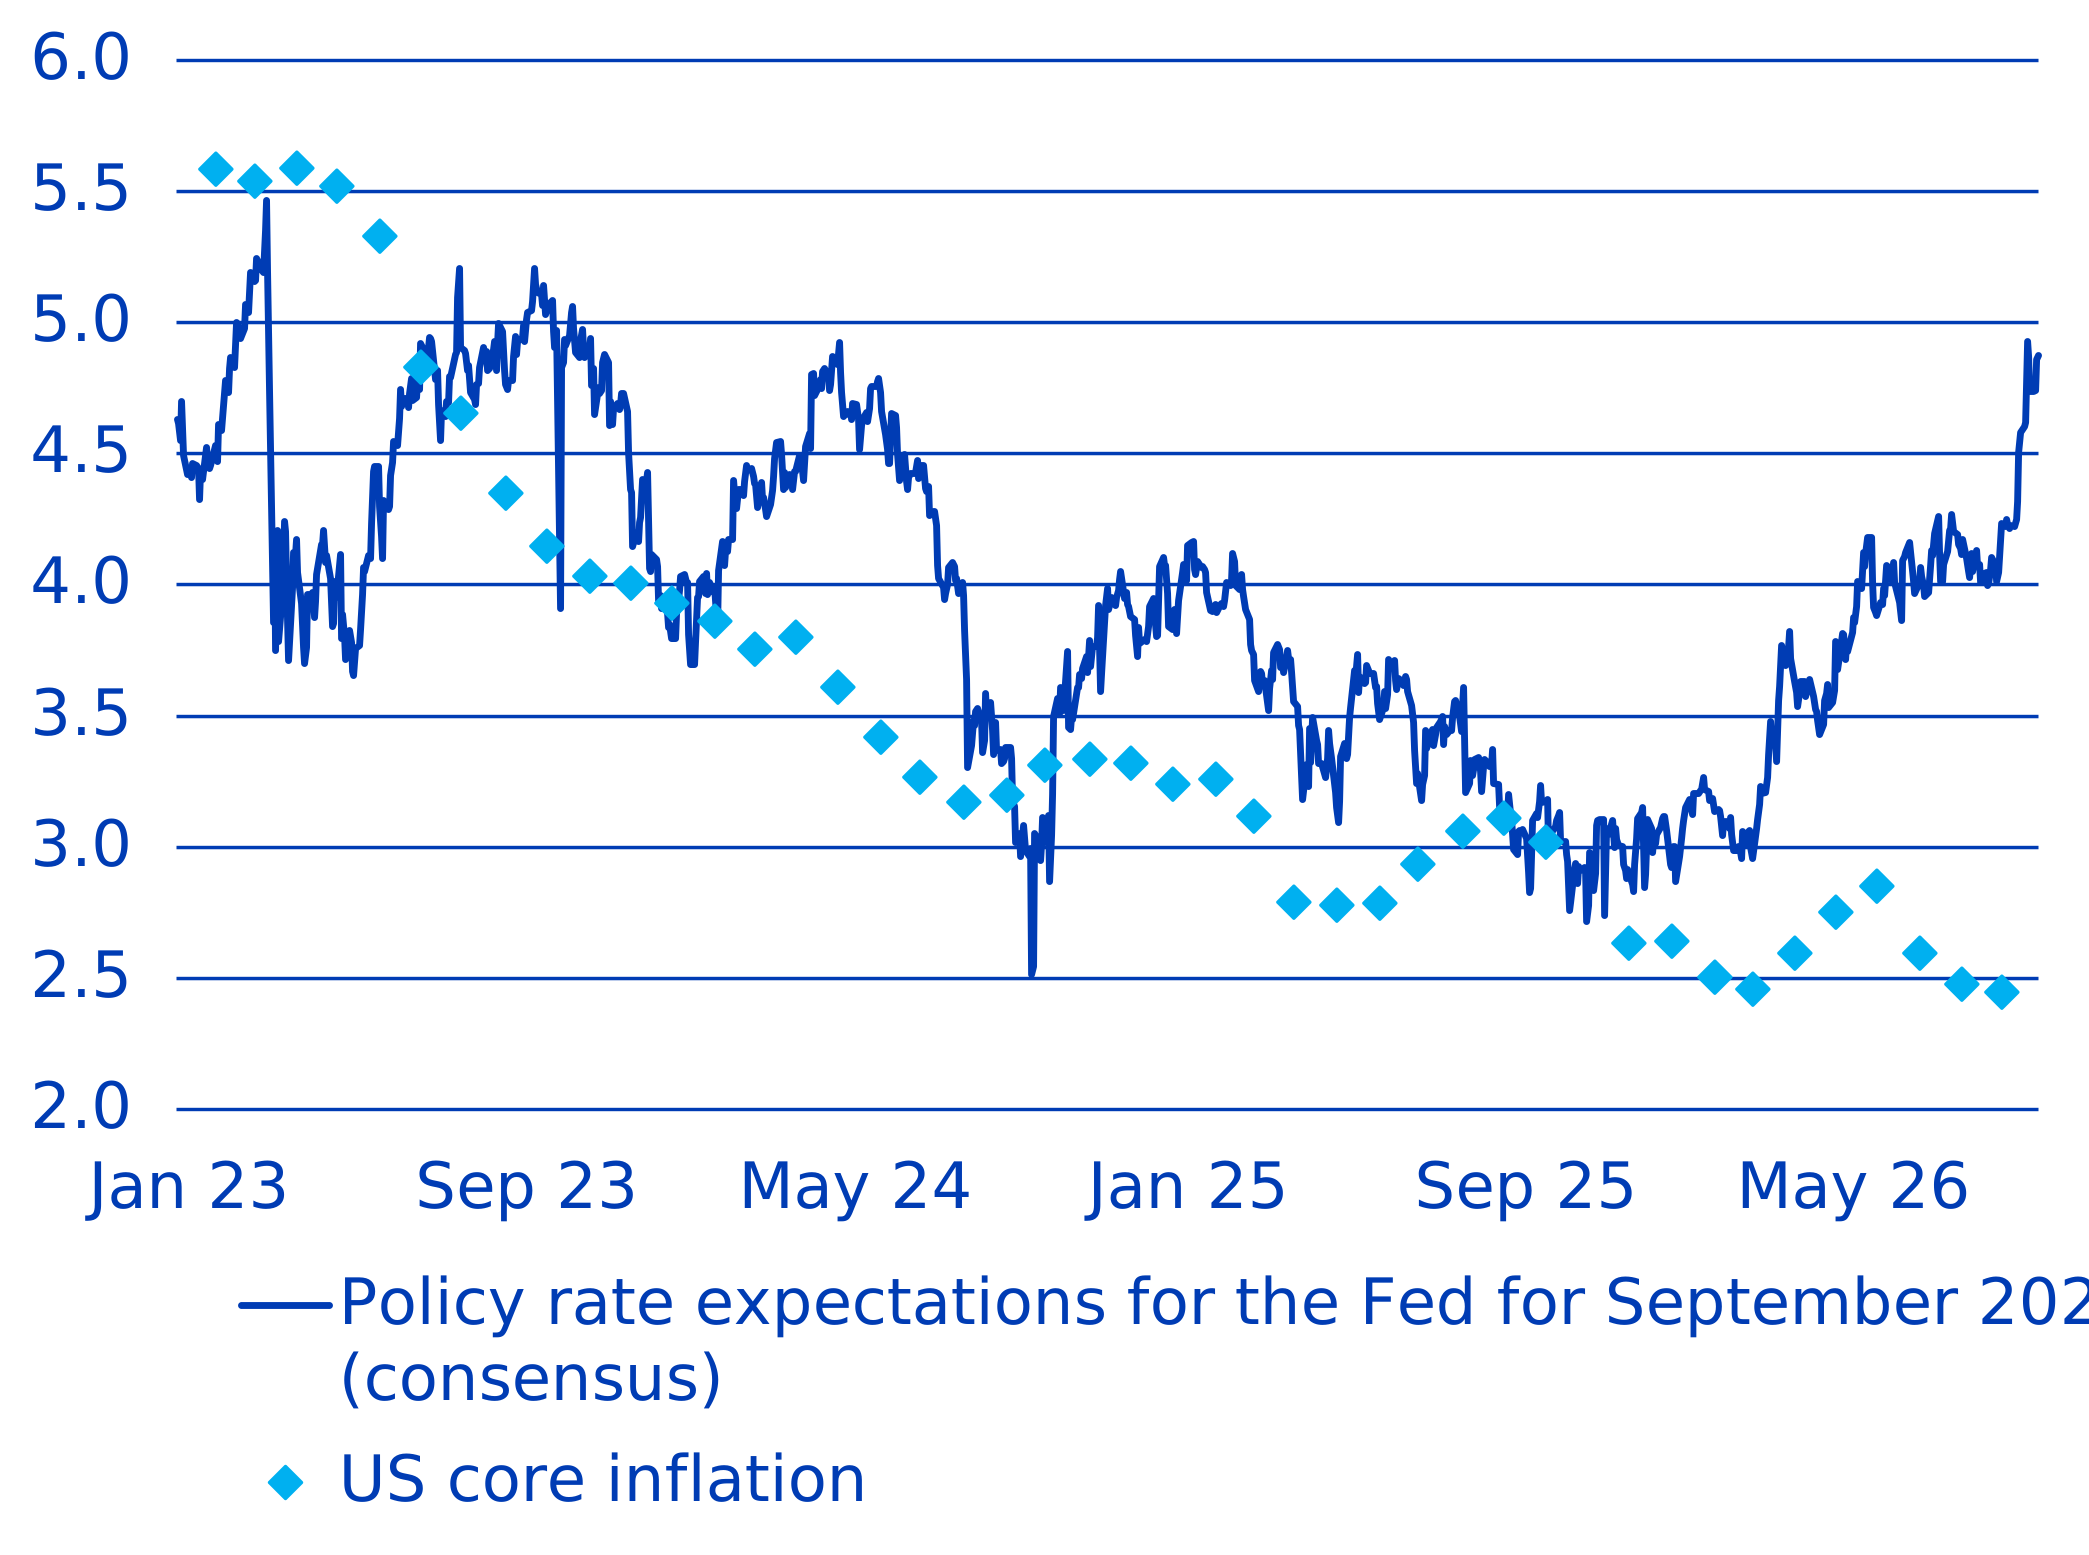
September was eventful. Contrary to our expectations, the situation in Iran has escalated. As a result, the oil price is again trading close to the macroeconomically critical threshold of USD 100. In combination with robust US economic data (US PMIs > 58), this has led to a sharp rise in yields (US 10y > 5%). The market is now pricing in four additional rate hikes by the Federal Reserve (Fed) and the European Central Bank (ECB) (see chart). Although we also expect further rate hikes due to higher inflation rates, we consider market expectations to be exaggerated. Core inflation remains moderate and rate hikes have little impact in the event of an energy supply shock. In the eurozone in particular, rate hikes will trigger weaker economic growth. We therefore remain long duration in foreign bonds, especially in Australia. In CHF bonds we maintain a clear underweight, as the rise in yields there is now gaining momentum with a lag.

Fed policy rate expected to be significantly higher despite moderate core inflation


Source: Bloomberg, Zürcher Kantonalbank

Equities: tech once again the driving force

Despite the rise in yields and warnings from AI experts, tech was once again the clear winner in September. All other sectors ended the month in negative territory. Tech is therefore once again the driving force for the overall market. We are increasing our overweight by adding US equities.

The reasons:

  • earnings growth remains robust (US tech +71% in 2026)
  • sentiment is far from euphoric
  • valuations are moderate (P/E of 27 vs 40 a year ago)

While we are increasing our overweight in tech and cyclical stocks in our portfolio, we remain underweight in Swiss equities in view of their high valuations and defensive sector composition.

Alternative investments: silver more attractive than real estate

We are not making any changes to alternative investments. We are confirming our slight underweight in listed Swiss real estate. The combination of high premia, numerous capital increases and the global rise in yields is weighing on the market. This is reflected in the decline of the benchmark, the SWIIT index, which has fallen by -3% since the beginning of the year. However, seasonally stronger months are now ahead, as prices usually pick up again towards the end of the year.

In commodities, we continue to favour silver, while we still expect oil prices to fall. However, as the situation is very volatile and unpredictable due to the war involving Iran, we are remaining neutral in commodities for the time being. We are maintaining an overweight in catastrophe bonds, which are currently in the most interesting phase of the year (hurricane season).

Foreign currencies: USD building momentum, CHF tending to weaken

We are reducing our underweight in USD. In return, we are downgrading CHF, which is in a downward trend due to the high interest rate differential versus other currencies. This is likely to reverse next year, as we expect policy rate hikes by the Swiss National Bank (SNB) and fewer rate hikes by the Fed. This will, however, require somewhat weaker economic data. Our favourite currency remains AUD, which is benefiting from high commodity prices and high carry. We are also overweight in emerging-market currencies and CAD.

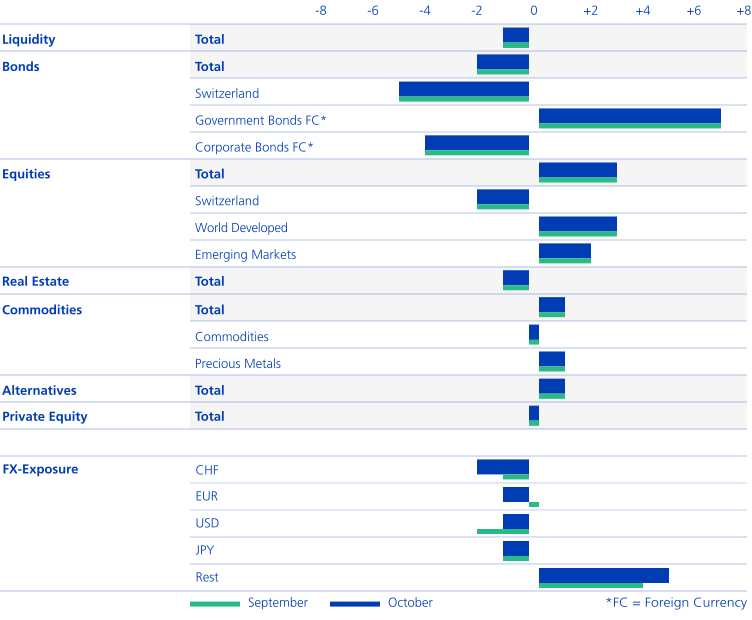
Our Tactical Asset Allocation in October 2026


Relative weighting vs. Strategic Asset Allocation (SAA) in % in September and October 2026 (Source: Zürcher Kantonalbank, Asset Management)

Legal Notice

“BLOOMBERG®” and the Bloomberg indices listed herein (the “Indices”) are service marks of Bloomberg Finance L.P. and its affiliates, including Bloomberg Index Services Limited (“BISL”), the administrator of the Indices (collectively, “Bloomberg”) and have been licensed for use for certain purposes by the distributor hereof (the “Licensee”). Bloomberg is not affiliated with Licensee, and Bloomberg does not approve, endorse, review, or recommend the financial products named herein (the “Products”). Bloomberg does not guarantee the timeliness, accuracy, or completeness of any data or information relating to the Products.

This document is for information and advertising purposes only. It is intended for distribution in Switzerland and is not intended for investors in other countries.

It does not constitute an offer or a recommendation to purchase, hold or sell financial instruments or to obtain products or services, nor does it form the basis for a contract or an obligation of any kind.  The recip-ient is advised to review the information, possibly with the assistance of an advisor, to determine its com-patibility with their personal circumstances as well as its legal, regulatory, tax, and other implications. The information contained in this publication may be adjusted at any time.

The document was prepared by Zürcher Kantonalbank with customary due diligence and may contain information from carefully selected third-party sources. However, Zürcher Kantonalbank provides no warranty as to the correctness and completeness of the information contained therein and accepts no liability for damages resulting from the use of the document or information contained therein.

Unless otherwise stated, the information refers to Zürcher Kantonalbank's asset management under the Swisscanto brand, which primarily includes collective capital investments under Swiss, Luxembourg and Irish law (hereinafter referred to as "Swisscanto funds").

The investment opinions and assessments of securities and/or issuers contained in this document have not been prepared in accordance with the rules on the independence of financial analysts and therefore constitute marketing communications (and not independent financial analysis). In particular, the employees re-sponsible for such opinions and assessments are not necessarily subject to restrictions on trading in the relevant securities and may in principle conduct their own transactions or transactions for Zürcher Kantonalbank in these securities.

The sole binding basis for purchasing Swisscanto funds is the current fund documents (e.g. fund agreements/contractual conditions, prospectuses, key investor information or basic information sheets as well as annual reports), which can be obtained from products.swisscanto.com, Swisscanto Fund Management Company Ltd., Bahnhofstrasse 9, CH-8001 Zurich (also representative of the Luxembourg Swisscanto funds) or from all branch offices of Zürcher Kantonalbank. The paying agent for the Luxembourg Swisscanto funds in Switzerland is Zürcher Kantonalbank, Bahnhofstrasse 9, CH-8001 Zurich.

It should be noted that any information about historical performance does not indicate current or future performance, and any performance data provided may not consider the commissions and costs incurred when issuing and redeeming fund units. Any estimates regarding future returns and risks contained in the document are for informational purposes only. Zürcher Kantonalbank does not provide any guarantee for this.

Every investment involves risks, especially with regard to fluctuations in value and return.

The products and services described in this publication are not available to US persons in accordance with the applicable regulations. This publication and the information contained in it must not be distributed and/or redistributed to, used or relied upon by, any person (whether individual or entity) who may be a US person under Regulation S of the US Securities Act of 1933. US persons include any US resident; any corporation, company, partnership or other entity organized under any law of the United States; and other categories set out in Regulation S. Status of the data (unless otherwise stated): 03.2026

© 2026 Zürcher Kantonalbank. All rights reserved.

Categories

Investment Strategy